
The Psychology of Money study guide · Lesson 5 of 6
Behavioral Efficiency: Savings, Reasonableness, and Error Margins
The Efficiency of Saving & Reasonable vs. Rational Decisions · Room for Error, Margin of Safety, and Long-Term Evolution
Unofficial study guide for The Psychology of Money: Timeless lessons on wealth, greed, and happiness by Morgan Housel. FlashFeed is not affiliated with the author or publisher.
This is the lesson's study guide from the FlashFeed app, plus its key facts and a self-test.
What you'll be able to do
- Explain why saving money is an efficiency of spending, and distinguish being Reasonable from strictly Rational financial models.
- Apply Graham's margin of safety (the Russian roulette bet, lower-return planning, cash savings), and spot the End of History Illusion and the sunk cost fallacy.
Lesson 5: Behavioral Efficiency: Savings, Reasonableness, and Error Margins
Welcome to Lesson 5 of The Psychology of Money. This lesson analyzes the efficiency of personal savings rates, contrasts reasonable versus rational decision-making, and establishes the foundational importance of room for error.
The Efficiency of Saving & Reasonable vs. Rational Decisions
Building wealth has far more to do with your personal Savings Rate than your investment returns or your gross income level. You can build substantial wealth on a modest income if you maintain a high savings rate, but you have zero chance of building wealth on a high income if your spending matches or exceeds what you earn.
Past a basic level of physical comfort, spending is driven by ego. Your savings rate is simply the gap between your ego and your income. Learning to be happy with less money creates a powerful double benefit: it frees up capital to invest and permanently lowers the amount of money you need to live comfortably.
Crucially, you do not need a specific purchase goal (such as buying a car or a house) to save money. Saving for the Sake of Saving buys unallocated flexibility, optionality, and liquidity. In an unpredictable global economy, having liquid cash gives you the power of patience: the ability to wait for rare opportunities and withstand sudden crises without forced liquidation.
Chapter 11 contrasts two approaches to financial decision-making: being Coldly Rational versus being Comfortably Reasonable. Academic economists design mathematical models assuming that human beings are rational utility-maximizing robots. But real human beings are emotional, social creatures with families, fears, and pride. Coldly rational financial strategies often fail because they ignore the psychological friction of real life.
A reasonable financial plan that lets you sleep peacefully at night and stick with it through severe market drawdowns will dramatically outperform a mathematically optimal plan you abandon in terror.
In 1917, Austrian physician Julius Wagner-Jauregg pioneered malaria fever therapy to treat neurosyphilis, work that won him the Nobel Prize in Medicine a decade later, in 1927. Wagner-Jauregg recognized that a high biological fever, while painful and dangerous, is a natural evolutionary mechanism that kills invading bacteria. Market volatility and drawdowns are the financial equivalent of fevers: uncomfortable and distressing, but a natural and necessary part of the long-term compounding process.
Academic theorists (a 2008 Yale study by Ian Ayres and Barry Nalebuff) recommend that young investors use two-to-one margin on stocks, arguing the strategy raises expected retirement wealth by 90% over a lifetime. While mathematically rational on paper, this strategy is emotionally impossible for real human beings to endure: with two-to-one leverage, a 50% market drop wipes out 100% of the account, and no normal person can watch their retirement savings evaporate entirely without abandoning the plan.
The Sleep at Night Test is Housel's favored benchmark for any personal portfolio allocation. Paying off a low-interest mortgage or holding extra cash may be mathematically sub-optimal compared to holding index funds, but if it eliminates anxiety and ensures sound sleep, it is completely reasonable.
Ego, Savings Efficiency, and the Sleep-at-Night Metric
The mathematical beauty of a high Savings Rate is that it operates as a dual lever for wealth creation: it accelerates the accumulation of investment capital while simultaneously reducing the annual cost of your lifestyle. If your household can live happily on 70% of your income, you save 30% of your salary and only need an investment portfolio large enough to generate 70% of your current earnings in retirement.
Furthermore, evaluating financial strategies through the lens of Comfortably Reasonable rather than Coldly Rational ensures behavioral compliance during severe market downturns. A mathematically optimal portfolio that induces sleepless nights, panic, and anxiety will inevitably be sold at the bottom of a bear market. In contrast, a reasonable portfolio—one that includes extra cash reserves, zero high-interest debt, or a paid-off primary residence—provides the emotional peace of mind required to remain calm, patient, and invested when markets plummet.
Room for Error, Margin of Safety, and Long-Term Evolution
Chapter 12 explores the fallacy of relying on historical data to predict future market behavior. History is the Study of Surprising Events. Economies, technologies, regulations, and consumer behaviors constantly evolve. Using past market patterns as a strict blueprint for future probabilities is flawed because the future will inevitably produce unprecedented black swan events. Historians make poor prophets.
Chapter 13 outlines the foundational principle of investing: Benjamin Graham's concept of the Margin of Safety, or Room for Error.
Room for error is not a conservative compromise; it is an active mechanism that prevents unexpected shocks from wiping out your ability to stay in the game. Having a margin of safety means designing your financial plan so that you can still achieve your goals even if your future investment returns are one-third (about 33%) lower than historical averages.
Avoid single points of failure in personal finance: relying on a single asset class, a single employer, or zero cash liquidity invites catastrophe. The Russian Roulette thought experiment demonstrates this principle: even if a risky bet has a 95% chance of making you a millionaire, a 5% chance of total ruin makes it completely unacceptable.
Chapter 14 addresses the psychology of personal evolution. Psychologist Daniel Gilbert discovered the End of History Illusion: humans readily acknowledge how much they have changed in the past decade, but consistently underestimate how much their desires, values, and goals will change in the future.
Because personal goals and family priorities evolve drastically over a lifetime, long-term financial plans must maintain structural flexibility. Avoid extreme financial commitments on either end of the spectrum: extreme frugality breeds later regret, while extreme workaholic hours lead to midlife burnout.
The Sunk Cost Fallacy traps investors into clinging to obsolete past choices out of emotional reluctance to admit a mistake. Accepting the reality of personal evolution gives you permission to abandon outdated past goals without guilt. A good financial plan does not pretend to know what the future holds; it creates resilience so that whatever happens, you can endure and adapt. Cash savings represent the ultimate margin of safety, transforming potential life catastrophes into manageable inconveniences.
The Philosophy of Room for Error and Life Evolution
Benjamin Graham's concept of the Margin of Safety is the ultimate behavioral shield against life's unpredictable shocks. Because the future will inevitably produce unprecedented economic crises, health emergencies, and technological disruptions, financial plans must never be constructed under assumptions of historical return perfection. Designing plans that succeed even if future returns lag historical averages by one-third ensures lifelong resilience.
Moreover, acknowledging the End of History Illusion—the psychological tendency to believe that your current values, desires, and career aspirations are permanent—demands that personal financial plans maintain structural flexibility. Avoid irreversible financial commitments and extreme lifestyle dogmas. By building generous cash buffers, keeping fixed overhead low, and accepting that personal desires will evolve over time, you create an adaptable financial system capable of supporting your happiness across every stage of life.
Practical Implementation of Margin of Safety
To operationalize room for error in household finance, consider maintaining three defensive layers (an illustrative checklist built on the margin-of-safety idea; the 6-to-12 month reserve and the 50% overhead cap are this guide's own example thresholds, not figures from the book):
- The Cash Resilience Layer: A dedicated 6-to-12 month cash reserve held outside the stock market.
- The Under-Optimization Layer: Assuming portfolio returns will lag historical market benchmarks by about one-third, ensuring retirement goals are met even during secular stagnation.
- The Overhead Flexibility Layer: Keeping recurring fixed monthly expenses (housing, auto loans, subscriptions) below 50% of take-home pay, allowing rapid budget contraction during economic emergencies.
Key terms
- The Ego-Income Gap
- Housel's definition of savings rate: the gap between your income and your ego's demand for status consumption.
- Wagner-Jauregg's Fever Discovery
- The 1927 Nobel Prize-winning medicine breakthrough proving that a painful biological fever is a natural mechanism that fights infection.
- The Sleep-at-Night Test
- Housel's guiding principle for portfolio decisions: structure your investments so you can sleep peacefully without financial anxiety, even if it means a mathematically suboptimal choice.
- Graham's Room for Error
- Benjamin Graham's foundational rule that every financial calculation must incorporate a generous buffer for being wrong.
- The End of History Illusion
- Psychologist Daniel Gilbert's discovery that humans acknowledge past personal changes but underestimate how much their desires will evolve in the future.
- The Sunk Cost Trap
- Clinging to obsolete past careers, businesses, or investments out of emotional reluctance to admit that initial plans have run their course.
Key facts
The Savings Rate Imperative
You can build wealth on a modest income with a high savings rate, but cannot build wealth on high income if spending matches earnings.
Saving for the Sake of Saving
You do not need a specific goal to save money; saving for the sake of saving buys unallocated flexibility, optionality, and liquidity.
The Competitive Advantage of Liquid Cash
In an unpredictable global economy, liquid savings provide a competitive edge by enabling patience and avoiding forced liquidation.
Coldly Rational
Coldly rational plans optimize mathematical equations on paper, whereas comfortably reasonable plans optimize for emotional peace and real-world adherence.
The Brittleness of Cold Rationality
Coldly rational financial models ignore human emotion and family dynamics, making them brittle and difficult to sustain during panics.
Market Volatility as an Economic Fever
Market drawdowns are an uncomfortable but unavoidable part of investing; trying to eliminate them entirely, like suppressing a healthy fever, can do more harm than good.
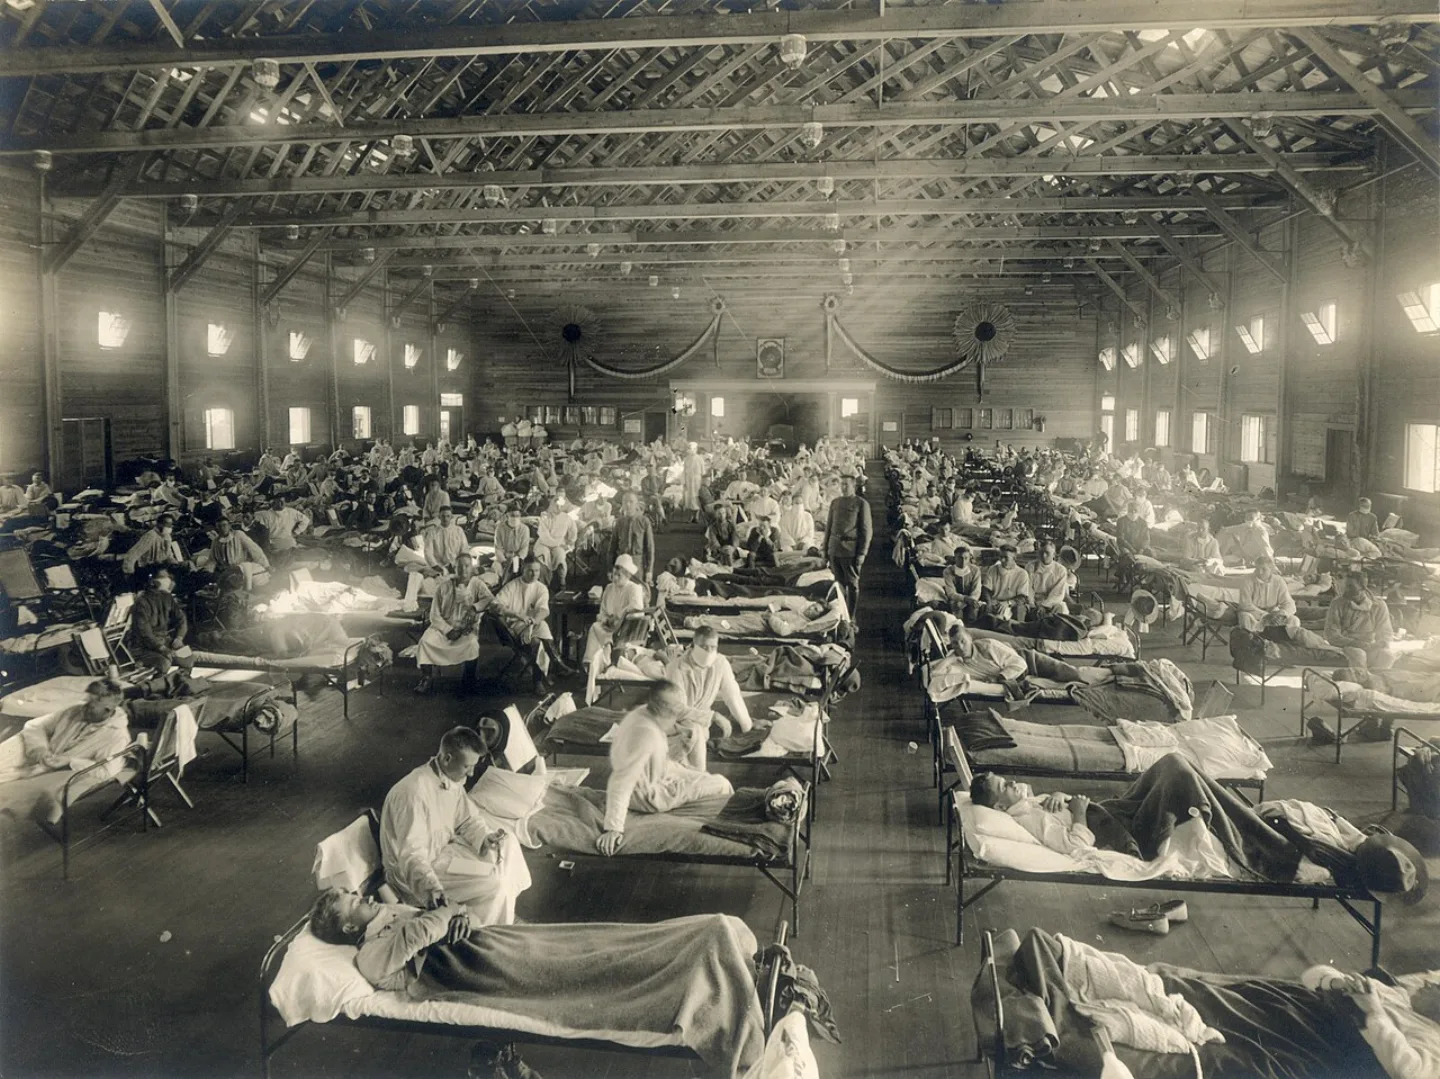
The Historian's Fallacy
Historians make poor prophets because unprecedented black swan events (pandemics, wars, breakthroughs) drive most historical shifts.
Room for Error as an Active Weapon
Room for error is not a conservative compromise; it is an active mechanism that prevents unexpected shocks from ending your ability to play.
Eliminating Single Points of Ruin
Avoid single points of failure in personal finance: relying on a single asset class, single employer, or zero cash liquidity invites ruin.
The Necessity of Structural Flexibility
Because personal goals and family priorities evolve drastically over a lifetime, long-term financial plans must maintain flexibility.
Extreme Frugality
Extreme frugality breeds later regret over missed youth and experiences, while extreme workaholism leads to midlife burnout and broken relationships.
Permission to Evolve
Accepting personal evolution gives individuals permission to abandon outdated past career and financial goals without guilt.
Resilience Over Accurate Prediction
A good financial plan does not pretend to know the future; it creates resilience so that whatever happens, you can endure and adapt.
Avoiding Single Points of Failure
Relying on a single income source, zero cash liquidity, or concentrated equity positions creates extreme vulnerability to ruin.
Step by step
Designing a Capitulation-Proof Portfolio
- Identify the maximum historical drawdown you can emotionally endure without losing sleep
- Calibrate your equity-to-cash allocation to ensure paper losses remain within your emotional threshold
- Eliminate all margin borrowing to remove the threat of sudden broker liquidation calls
- Review your portfolio infrequently to minimize the psychological pain of daily market volatility
Navigating Multi-Decade Personal Evolution
- Avoid making extreme, irreversible lifestyle or career commitments in your twenties and thirties
- Revisit personal financial goals every few years to align with evolving family values and interests
- Abandon obsolete investments and career paths without feeling bound by historical sunk costs
- Maintain cash buffers and low fixed overhead to preserve the freedom to pivot when desires change
Self-test
Answer each question from memory, then check your work against the answer key.
1. According to Housel, which factor matters most for building wealth?
- AIncome Level
- BPortfolio Diversification
- CInvestment Returns
- DSavings Rate
2. Which of these is NOT a benefit the lesson attributes to 'saving for the sake of saving'?
- AGuaranteed higher returns
- BOptionality
- CLiquidity
- DUnallocated flexibility
3. Which term describes a strategy that optimizes the math while ignoring the emotional and family side of real life?
- AMargin of Safety
- BThe Sleep-at-Night Test
- CColdly Rational
- DComfortably Reasonable
4. Learning to be happy with less money creates what kind of benefit for wealth building?
- AA one-time benefit
- BA double benefit
- CA short-term benefit
- DA tax benefit
5. Which condition did Wagner-Jauregg's Nobel Prize-winning fever therapy treat, used as an analogy for market volatility?
- ASmallpox
- BMalaria
- CTuberculosis
- DNeurosyphilis
6. Whose foundational concept is the 'Margin of Safety,' or Room for Error, described in Chapter 13?
- ABenjamin Graham
- BMorgan Housel
- CJulius Wagner-Jauregg
- DDaniel Gilbert
7. Which of these is NOT a single point of failure in personal finance?
- AZero cash liquidity
- BA single asset class
- CA diversified portfolio
- DA single employer
8. In the Russian Roulette thought experiment, what chance of total ruin makes an otherwise attractive bet unacceptable?
- A20 percent
- B5 percent
- C1 percent
- D50 percent
9. Daniel Gilbert's 'End of History Illusion' describes people's tendency to do what?
- AOverestimate future returns
- BUnderestimate future desire changes
- CIgnore sunk costs
- DOverestimate past achievements
10. An investor keeps funding a failing business only because of years already invested, refusing to admit the plan failed. This illustrates which concept?
- AThe End of History Illusion
- BThe Historian's Fallacy
- CRoom for Error
- DThe Sunk Cost Trap
Go deeper
- ReadThe Psychology of Money by Morgan Housel · on Amazon ↗
- StudyThe Psychology of Money in the FlashFeed app
These are affiliate links: if you buy a book through one, FlashFeed may earn a small commission at no extra cost to you. The commission helps pay for FlashFeed's servers.
As an Amazon Associate we earn from qualifying purchases.
Answer key
- 1. D Savings RateHousel argues savings rate matters more than returns or income: a high income with matching spending builds no wealth, while a modest income with a high savings rate can.
- 2. A Guaranteed higher returnsSaving without a specific goal buys flexibility, optionality, and liquidity, not higher investment returns, which is a separate and unrelated benefit.
- 3. C Coldly RationalColdly rational plans optimize the math while ignoring emotion and family dynamics, making them brittle and prone to abandonment during panics, unlike comfortably reasonable plans.
- 4. B A double benefitIt is a double benefit: it frees up capital to invest while also permanently lowering the amount of money needed to live comfortably.
- 5. D NeurosyphilisWagner-Jauregg treated neurosyphilis by inducing malaria to create a fever; malaria was the treatment mechanism, not the disease being cured.
- 6. A Benjamin GrahamBenjamin Graham's Margin of Safety concept requires every financial calculation to include a generous buffer for being wrong.
- 7. C A diversified portfolioRelying on a single asset class, single employer, or zero cash liquidity creates a single point of failure; a diversified portfolio is the opposite of a point of failure.
- 8. B 5 percentEven a 95 percent chance of becoming a millionaire is unacceptable if there is a 5 percent chance of total ruin, since ruin ends your ability to keep playing.
- 9. B Underestimate future desire changesGilbert found people readily see how much they've changed in the past but underestimate how much their desires and goals will change in the future.
- 10. D The Sunk Cost TrapThe Sunk Cost Trap describes clinging to obsolete past choices out of emotional reluctance to admit a mistake, unlike Room for Error or the Historian's Fallacy.
Sources
- The Psychology of Money — Morgan Housel
- Morgan Housel, The Psychology of Money, Chapter 10
- Morgan Housel, The Psychology of Money, Chapter 11
- Morgan Housel, The Psychology of Money, Chapter 12
- Morgan Housel, The Psychology of Money, Chapter 13
- Morgan Housel, The Psychology of Money, Chapter 14
- Morgan Housel, The Psychology of Money, Chapter 5
Image credits
- The Historian's Fallacy: Otis Historical Archives, National Museum of Health and Medicine · Public domain — commons.wikimedia.org/wiki/File:Emergency_hospital_during_Influenza_epidemic,_Camp_Funston,_Kansas_-_NCP_1603.jpg
